Whole life insurance vs term life insurance: Which is the better choice for you?
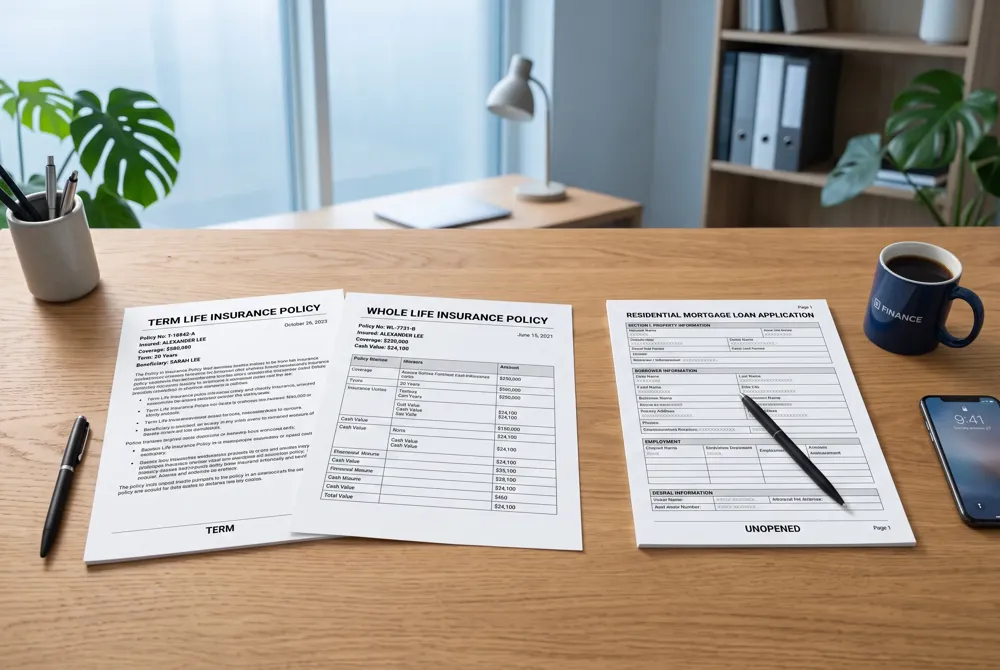
Two Products, One Question: Which Policy Fits?
Every credit union member shopping for life insurance faces the same fork: term life insurance or whole life insurance. These two product lines answer different financial needs and fit different budgets.
Term life insurance provides coverage for a set period (typically 10 to 30 years) at a low initial premium. Whole life insurance offers permanent protection for the member's entire lifetime at a higher, fixed premium, and includes a cash value component that grows over time on a tax-deferred basis, as defined by Investopedia.
The choice matters. This article breaks down the costs, features, trade-offs, and practical guidance you can use to help your members select the right coverage.
Term Life Insurance Basics
Term life insurance is a temporary policy that provides coverage for a defined period, typically 10 to 30 years. It pays a death benefit only if the policyholder dies within that term. If the policyholder outlives the term, coverage ends and no benefit is paid.
The structure is simple. There is no cash value component, no savings element, and no investment feature. Premiums are fixed for the duration of the term and are generally the lowest of any life insurance type. For a healthy 40-year-old, a $500,000, 20-year term policy costs about $321 per year, compared to roughly $3,180 per year for a whole life policy with the same death benefit.
Term life insurance is the most cost-effective way to provide pure protection for a temporary obligation, such as covering a mortgage, replacing income during working years, or funding a child's education. It is often the right starting point for members who need substantial coverage on a limited budget.
Whole Life Insurance Basics
Whole life insurance is a permanent coverage product that credit unions can offer to members. As long as premiums are paid, the death benefit is guaranteed to be paid to the beneficiary, regardless of when the member passes away. Unlike term insurance, there is no expiration date.
A core feature of whole life insurance is its cash value component. A portion of each premium is allocated to a tax-deferred savings account that grows at a guaranteed rate set by the insurer. Members can access this cash value through loans or withdrawals, though doing so reduces the death benefit.
Both premiums and the death benefit remain fixed for the life of the policy. This predictability makes whole life insurance a conservative option for members who want lifelong protection and a tax-advantaged savings vehicle. However, these guarantees come at a cost: whole life premiums are significantly higher than term life premiums for the same initial death benefit, often five to fifteen times more depending on age and health.
Some policies from mutual insurers may also pay annual dividends, though these are not guaranteed. For example, some mutual insurers have paid dividends consistently for over a century, adding to cash value growth.
Where Term Life Wins
For a credit union member who needs coverage for a defined period, term life insurance is often the most practical choice. It delivers the largest death benefit for the lowest premium, which is why it remains the most popular form of life insurance in the United States. A healthy 30-year-old non-smoking man can secure a 30-year, $250,000 term life insurance policy for an average of $18 per month. At age 50, the same coverage costs roughly $67 per month. Whole life insurance covering the same individual would cost roughly $100 per month for only $100,000 in coverage.
Term life insurance is the right fit when the need for protection is temporary and the budget is tight. Common scenarios include covering a mortgage balance, replacing income while children are growing up, or paying for college tuition. In these cases, the member wants maximum protection during the years when a loss would be most damaging, then lets the coverage expire when the financial obligation is gone. There is no cash value component, so premiums stay low.
For younger families with limited cash flow, the low cost of term life insurance makes it accessible. Many members can afford a $500,000 20-year term policy for a few hundred dollars a year. Whole life insurance with the same death benefit would cost thousands of dollars annually. The gap in premiums means the member can put the difference toward other financial priorities, such as retirement savings or an emergency fund.
Many term life insurance policies include a conversion rider that allows the member to switch to a whole life insurance policy later without a new medical exam. This feature gives a younger, healthy member the ability to lock in low rates now while preserving the option to obtain permanent coverage in the future if health or financial goals change. Credit unions that offer term life insurance alongside whole life insurance allow members to match the product to their life stage rather than forcing a one-size-fits-all decision.
Where Whole Life Wins
Whole life insurance guarantees permanent coverage. As long as premiums are paid, the policy never expires and the death benefit is certain to reach beneficiaries. This stands in contrast to term life insurance, which ends after a set period and leaves no value if the member outlives the term.
Beyond the death benefit, whole life insurance builds a cash value component that grows at a guaranteed, tax-deferred rate. Policyholders can access that cash value through loans or withdrawals, using it for expenses like college tuition or retirement income without the market risk of a stock portfolio. The growth is insulated from market fluctuations, a feature that appeals to members seeking predictable, low-volatility savings.
Whole life insurance is ideal for estate planning and leaving a tax-free legacy. The death benefit passes to beneficiaries income-tax-free, making it a natural vehicle for funding a special needs trust or covering estate taxes. Members who want to ensure lifetime support for a dependent, such as a child with disabilities, may find whole life the only suitable choice.
The Cost Difference by the Numbers
Whole life insurance costs 5 to 15 times more than term life insurance for the same death benefit. The price gap is widest for younger buyers and narrows at older ages, but it remains substantial across every age bracket.
Sample $500,000 Policy Premiums
For a healthy 30-year-old man, a $500,000 term life policy costs roughly $28 per month. A whole life policy with the same $500,000 face amount costs approximately $400 per month, according to mid-2026 market rates from major carriers. A 40-year-old man paying level term premiums sees a similar ratio: about $54 per month for a 20-year term versus roughly $460 per month for whole life.
At age 60, the same man would pay about $228 per month for a 20-year term policy. A whole life policy at that age jumps to roughly $1,360 per month. Women pay less at every age. A 30-year-old woman in good health can expect roughly $344 per month for a $500,000 whole life policy, compared to about $22 per month for term.
Why the Gap Exists
Whole life premiums lock in at the age of application and never increase. A portion of every premium funds a cash value account that grows on a tax-deferred basis. Term life premiums are also level for the duration of the term, but they cover only the death benefit with no savings component. Once the term ends, renewal carries much higher premiums based on the policyholder's then-current age and health. Whole life's permanent coverage and cash value feature drive the higher upfront cost.
| Age | Gender | Term (20yr, $500K) | Whole Life ($500K) | Cost Ratio |
|---|---|---|---|---|
| 30 | Male | $28/mo | $400/mo | 14x |
| 40 | Male | $54/mo | $460/mo | 8.5x |
| 60 | Male | $228/mo | $1,360/mo | 6x |
| 30 | Female | $22/mo | $344/mo | 16x |
| 40 | Female | $46/mo | $415/mo | 9x |
| 60 | Female | $190/mo | $1,200/mo | 6.3x |
For a credit union advising members, the choice depends on whether the member wants maximum death benefit for the lowest cost or lifelong coverage with cash value accumulation. Term life is the practical option for temporary needs like mortgage protection or income replacement during working years. Whole life suits members who want guaranteed lifetime coverage and are prepared to pay the premium difference.
Disadvantages of Whole Life
The main catch of whole life insurance is its cost. Premiums are often 5 to 15 times higher than term life insurance for the same death benefit, because the payment covers not just insurance risk but also cash value funding, administrative fees, and agent commissions.
Cash value grows slowly in the early years. Policyholders may pay thousands in premiums before any meaningful savings appear, largely because high upfront fees and commissions consume most of the first several years' payments. Borrowing against the cash value reduces the death benefit if the loan is not repaid, and surrendering the policy triggers taxable income on any gains.
Whole life has a rigid premium structure. The fixed payment cannot be lowered if a member's finances change, and the policy requires a long-term commitment that many may not need. For a credit union advising members, term life insurance offers a simple, affordable alternative that covers specific obligations without these trade-offs.
Disadvantages of Term Life
Term life insurance has a straightforward disadvantage: it is pure protection with no savings component. If a member outlives the policy term, the coverage ends and no benefit is paid. The premiums that were paid do not accumulate into any cash value.
Unlike whole life insurance, a term policy offers no surrender value, no ability to borrow, and no payout beyond the death benefit during the covered period. The premiums are effectively consumed as the cost of risk protection.
Renewing or replacing a term policy after the initial period can be costly. Premiums rise sharply because the member is older and may have developed new health conditions. A new medical exam is typically required, and if health has declined, the member may become uninsurable at any reasonable price.
For a credit union recommending insurance to members, this temporary, pure-risk structure means term life insurance is best suited for short-term needs such as income replacement during working years or covering a mortgage. It does not support long-term wealth accumulation or legacy planning.
Why Critics Advise Against Whole Life
Prominent investors including Dave Ramsey and Warren Buffett have openly advised against whole life insurance. Their core argument: it unnecessarily bundles insurance and investing in a way that underperforms at both functions.
The premiums for whole life insurance are significantly higher than those for term life insurance. A large portion of early payments goes toward commissions and fees, not toward building cash value. Returns on the cash value component typically fall well short of what a simple low-cost index fund would generate over the same period.
For credit union members who need protection for a defined period, term life insurance offers simple, affordable coverage without an underperforming savings vehicle layered on top.
Converting Term to Whole Life
Many term life insurance policies include a conversion rider that lets the policyholder switch to a whole life insurance policy without undergoing a new medical exam. This option is useful if a member's health declines during the term period or if their estate planning needs change later on.
Conversion must happen before a specified deadline written into the policy. Some policies allow conversion only within the first few years. Others grant the right for the full term length if an extended conversion rider was purchased. Credit unions should advise members to check their specific policy terms and not assume the window is open indefinitely.
For a member whose health has deteriorated, conversion guarantees access to permanent coverage at standard premium rates tied to their original age at the time of the term policy purchase. This avoids the higher rates that would apply if they applied for a new whole life policy later. By understanding the conversion rider's rules, credit unions can help members hold onto affordable lifetime protection when they need it most.
Laddering Term and Whole Life Together
A single policy may not match a member's changing needs over time. Laddering combines a base whole life insurance policy with one or more term life insurance layers, creating a flexible coverage structure that adjusts as financial obligations shrink.
Base Layer. A whole life insurance policy covers the member for life, with level premiums and a cash value component. This guarantees permanent protection and leaves a tax-free death benefit regardless of when death occurs.Temporary Layers. One or more term life insurance policies (e.g., 10-year and 20-year terms) sit on top of the base. They provide high total coverage during peak earning and dependency years. As each term expires, total coverage drops, matching the declining need.Total Coverage. During the first decade, death benefit equals the sum of all layers. After the 10-year term ends, only the 20-year term and the whole life base remain. When the 20-year term expires, only the permanent whole life policy continues.
Laddering suits a member who needs heavy protection while raising children and paying a mortgage, but wants permanent coverage for estate planning or final expenses. It avoids overpaying for whole life on the full amount and avoids term only coverage that could leave a gap in later years.
This strategy works well for credit union members with stable incomes who can commit to whole life premiums for life. A credit union that partners with an insurance carrier can offer laddering as an education point during member conversations, helping members see how a mix of policy types fits their actual life timeline.
Guidance for Credit Union Members
For most credit union members, term life insurance is the practical choice during the years they carry a mortgage, have dependent children, or need income replacement. It delivers the largest death benefit per premium dollar for a defined period. Once that financial obligation ends, so does the need for coverage.Whole life insurance fits a narrower set of needs. It serves members with lifelong dependents, high net worth households pursuing estate planning, or those who want a guaranteed, tax-advantaged savings vehicle alongside permanent protection. The higher premiums are justified only when the need for coverage is permanent.
A 60-year-old member deciding between the two should weigh cost against duration. Term life insurance at that age carries a lower upfront premium but provides protection only for the selected term, typically 10 to 30 years. Whole life insurance costs more but guarantees lifelong coverage, builds cash value on a tax-deferred basis, and keeps premiums level regardless of age or health changes. The right answer depends on whether the need is time-limited, such as covering a surviving spouse's income gap, or permanent, such as leaving a legacy or funding a trust.
Credit unions that offer both term and whole life products position themselves to serve members at every life stage. A young family may need a large term policy to cover a mortgage and college costs. A retiree with assets may choose a smaller whole life policy for estate planning. Matching the product to the need helps members avoid overpaying for coverage they will outgrow or buying too little for obligations that persist.
Sample Premiums for Quick Reference
Premium examples help members see the price difference between term life insurance and whole life insurance at different ages. The gap is substantial, and buying early locks in lower rates for both products.
For a healthy 30-year-old non-smoker, a $100,000 20-year term life insurance policy costs roughly $15 to $25 per month. A $100,000 whole life insurance policy for the same person runs $100 to $120 per month, 4 to 6 times more. At $500,000 in coverage, the 30-year-old pays about $18 per month for term and $212 per month for whole life, a factor of 11 to 1.
By age 50, those numbers widen further. A $500,000 term policy costs about $68 per month, while a whole life policy for the same death benefit averages $729 per month. At age 60, a $500,000 whole life policy exceeds $1,000 per month; the equivalent 10-year term policy costs roughly $137 per month.
A 30-year-old who locks in a $500,000 whole life policy at $212 per month will pay that same premium at age 50, 60, and 80. A term policy holder at age 50 who needs new coverage after the initial term expires will reapply at the higher age-adjusted rate, paying $68 instead of $18 per month.
The takeaway is straightforward. Term life insurance offers the most death benefit per dollar for temporary needs. Whole life insurance costs more upfront but guarantees level premiums for life. For members who buy early, both products deliver lower rates. Delaying coverage means paying substantially more for the same protection.
Choosing the Right Coverage for Your Members
The central trade-off remains constant. Term life insurance delivers affordable temporary protection for a defined period.Whole life insurance provides permanent coverage but at a cost that can be 5 to 15 times higher.
Members make the best choice when they match a policy to a specific financial need and a realistic budget. A young family needing income replacement for 20 years is better served by a term policy. A member with a lifelong dependent may prefer the permanence of whole life.
Credit unions that offer both options position themselves as trusted partners. When members understand the trade-off between cost and duration, they make informed decisions. Offering both term and whole life insurance is one way to meet members’ needs at every life stage.
Related articles
7 Features to Look for in a Modern Consumer Lending Platform
Whole life insurance vs term life insurance: Which is the better choice for you?
What to Look for When Choosing Loan Processing Software for Your Bank
Ready to meet the AI-powered Loan Origination System?

