What to Expect When Moving Your Lending Operations to Modern Loan Origination Software
The Shift from Legacy to Modern
A loan origination system (LOS) automates the full lending lifecycle: application intake, credit scoring, underwriting, documentation, compliance checks, decisioning, and funding. Legacy systems from vendors like MeridianLink, Origence, or nCino often handle only pieces of that chain, forcing staff to move data between separate portals, decision engines, document systems, and account opening platforms.
That fragmentation creates real costs. Manual data entry slows cycle times. Disconnected systems produce errors and compliance gaps. Every handoff is a place where loans stall and members drop out. A modern LOS consolidates these functions into a single platform. Fuse replaces the separate applicant portal, decision engine, document automation tools, and account opening workspace with one AI-native system.
The result is faster processing and fewer dropped applications. Institutions like Vibrant Credit Union cut funding time from three days to 1.2 minutes after moving to a unified platform. For credit unions evaluating software, the core question is not whether automation matters, but whether the system delivers it as one cohesive stack or as another set of handoffs.
What a Loan Origination System Does
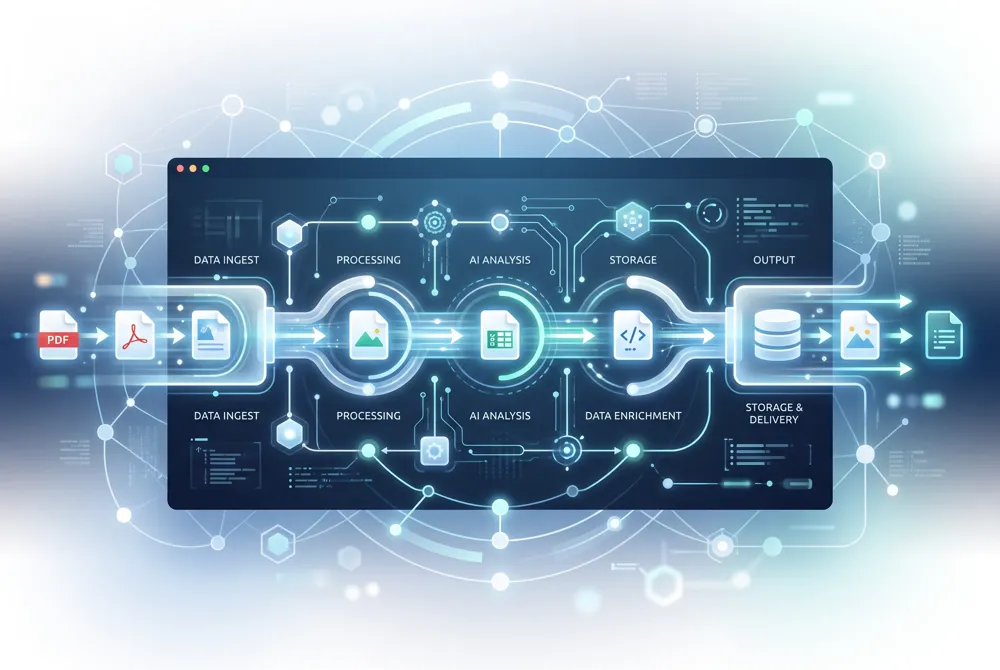
A loan origination system (LOS) is the software a financial institution uses to manage a loan from application through approval and funding. It handles borrower data collection, credit checks, document gathering, underwriting decisions, and compliance checks within a single digital workflow.
The process breaks into five distinct stages: pre-qualification, where a credit union gathers initial member information to estimate eligibility; application, which captures detailed financial data; processing, which involves verifying documents and ordering third-party checks; underwriting, where automated rules and AI agents assess risk against the institution's policies; and closing, which finalizes the loan and funds the member.
Before LOS platforms became standard, each of these stages ran on paper or on separate software modules. Loan officers manually generated documents using legal form templates, a slow and error-prone method. A credit union might use one system for the applicant portal, another for credit decisions, and a third for compliance checks, with data entered two or three times.
That fragmentation is still the norm at most community institutions. Legacy LOS platforms from vendors like MeridianLink, Origence, or nCino often require expensive implementation fees and charge extra for simple configuration changes. A modern loan origination system replaces those disjointed modules with a single platform that spans the entire lending workflow, from the member's first application to the final booking on the core.
Why Credit Unions Are Leaving Legacy LOS Behind
The numbers tell a stark story. Fintechs now hold nearly 40% of the consumer loan market. The number of federally insured credit unions has dropped by over 30% in the last decade. Legacy loan origination system vendors have not helped. They charge six-figure implementation fees and five-figure tolls for basic configuration changes. Contract friction becomes the primary lock-in mechanism, not product quality.
A modern loan origination system exists to close that gap. Fuse won the 2026 Callahan Innovation Award for Reimagining the Lending Experience, a recognition that highlights the difference between maintaining old infrastructure and building for the future. Instead of charging per workflow change or per integration, Fuse delivers a flat annual price with no implementation fee and no variable costs. The contractual Automation Guarantee covers three specific commitments: new integrations delivered in under one month, weekly product releases, and the ability to auto-decision on 100% of core data fields. That changes the economics of lending operations entirely.
Fuse replaces fragmented stacks from vendors like MeridianLink, Origence, and nCino with a single AI-native platform. Credit unions that switch gain predictable pricing, weekly releases, and a dedicated Automation Coach who helps identify the next highest-impact workflow to automate. The typical Fuse client achieves approximately 1% new automation per week, adding up to roughly 71% in the first year. That is not a contractual guarantee. It is an average outcome from institutions that have stopped accepting vendor lock-in as the cost of doing business.
What Modern LOS Replaces: Fragmented Stacks
Most credit unions run loan origination on a patchwork of disconnected systems: one portal for applicants, a separate decision engine, a document automation tool, and an account opening module that barely talks to the rest. Every handoff between these systems creates data entry, manual verification, and delays.
The operational cost of managing multiple systems shows up in staff hours wasted on re-keying data, compliance risk from mismatched information, and a fragmented member experience. One common setup pairs a core-provided LOS module from Jack Henry, Fiserv, or Corelation alongside MeridianLink or Origence for origination, plus a separate document platform. None of them share a single data model.
Fuse replaces these fragmented stacks with a single platform that spans the applicant portal, decision engine, document automation, agent workspace, and account opening. It sits on top of the core and handles the full lending workflow from application through funding. A credit union on a MeridianLink or Origence setup can replace those modules entirely. One on a Fiserv or Jack Henry core can run Fuse on top without touching the back-end.
The AI Agent Advantage: What They Actually Do
AI agents in modern loan origination software perform defined, narrow tasks. They read documents, extract data, verify fraud, auto-decision on core data fields, send outbound borrower communications, and recommend the next automation step via an Automation Copilot.
These agents apply configured rules and AI inference at the point of action. They do not learn from past outcomes, refine logic over time, or improve continuously. The boundary matters for compliance and auditability.
Legacy systems handle document verification manually, requiring staff to review each file. Fuse's AI agents automate this step, reducing the time from days to minutes.
Fuse's agents cover fraud verification, auto-decisioning on any core data field including custom attributes and charge-off history, and outbound borrower communications. The Automation Copilot surfaces the next highest-impact workflow, so operations teams know what to configure next.
The Two Automation Commitments
Moving to a modern loan origination system involves two distinct automation commitments from Fuse. They serve different purposes and should not be conflated.
Proactive Automation. Each client gets a dedicated Automation Coach who meets every two weeks to identify and ship the next highest-impact workflow. The typical outcome is approximately 1% new automation per week, or roughly 71% in the first year. These are average customer outcomes, not contractual guarantees.Automation Guaranteed. This is the contractual commitment written into every Fuse contract. It covers three items: new integrations delivered in under one month at no extra cost, weekly product releases, and the ability to auto-decision on 100% of core data fields. When writing about what is guaranteed, anchor on these three items only.
Pricing That Breaks the Legacy Model
Most loan origination system vendors charge six-figure implementation fees and demand additional payments for every configuration change. Fuse replaces that model with flat pricing: $100,000 per year for most credit unions, $50,000 for smaller institutions, with $0 implementation costs and $0 variable fees.
The pricing is not success-based or outcome-based. It is the same flat fee every year, regardless of loan volume, number of integrations, or automation usage. This stands in contrast to legacy vendors that charge per module, per user, per change order, and per integration.
In January 2026, FIS began reselling Fuse as an officially supported product, expanding distribution without changing the pricing model. Two months later, Fuse launched the $5M Rescue Fund: free access to the platform for the first 50 qualifying credit unions until their existing LOS contract expires, then a transition to the flat-fee subscription. Credit unions locked into multi-year legacy agreements with their current LOS vendor can start modernizing without paying twice.
For a credit union paying $200,000 or more per year for a legacy loan origination system plus implementation amortization and change-request fees, the all-in savings are immediate and predictable.
Real Results: Navigant, Canopy, and Vibrant
The claims around modern loan origination software are only as good as the outcomes they produce. Here are three Fuse customers, each representing a different scale and challenge, and the concrete results they have delivered.
Navigant Credit Union, with $4 billion in assets, launched a fully automated credit card program. The system handles end-to-end auto-decisioning on core data. No manual underwriting, no exception queue for standard applications.
Canopy Credit Union is a $200 million CDFI that spent five years unable to use auto-decisioning under its prior loan origination system. Within months of switching to Fuse, it turned on auto-decisioning and is on track to reach 40% auto-decisions within six months.
Vibrant Credit Union, using the Drivata auto-lending CUSO, cut funding time from three days to 1.2 minutes. Its indirect lending volume grew over 40% as a result.
These three institutions join more than 100 financial institutions that have adopted Fuse. Each result reflects a different starting point, but the pattern is the same: faster processing, higher automation, and measurable growth.
Pre-Built Integrations and No-Code Configuration
A modern loan origination software package is only as useful as the systems it connects to. Fuse ships with 200+ pre-built integrations covering core processors, credit bureaus, document storage, fraud detection, and e-signature vendors.
Every Fuse client benefits from no-code configuration. Business users adjust lending rules, workflows, and application screens without writing a line of code or opening a ticket with IT. Changes ship in hours, not months.
Under the Automation Guaranteed commitment, Fuse contractsually promises that new integrations are delivered in under one month at no extra cost. Product releases arrive every week, so the system never waits for a semi-annual update cycle to address a regulatory change or a new channel partner.
Backed by Investors Behind Chime and OpenAI
Fuse was founded in 2020 by co-CEOs Andrés Klaric and Marc Escapa and is headquartered in New York (legal entity Elsker Inc., DBA Fuse). The company has raised over $25 million from Footwork, Primary Venture Partners, NextView Ventures, Commerce Ventures, FJ Labs, and Clocktower. Clocktower is also an investor in Chime and OpenAI.
The Fuse platform is built on single-tenant, SOC 2 compliant infrastructure. The product ships weekly, and each release includes new features, integrations, and automation capabilities.
The Bottom Line
Moving to a modern loan origination system should deliver three things: a single platform that replaces a fragmented stack, AI agents that automate specific tasks without buzzwords, and a pricing model that does not punish growth. Fuse delivers each of these through a flat annual subscription, no implementation fees, and a contractual commitment to weekly releases, 100% core data auto-decisioning, and new integrations delivered within a month at no extra cost.
The typical Fuse customer achieves approximately 71% automation in the first year. Navigant Credit Union launched a fully automated credit card program. Canopy Credit Union, a CDFI, went from zero auto-decisions to a 40% rate in six months. These are not aspirational claims. They are outcomes from credit unions of different sizes and missions, all on the same flat-fee platform.
The gap between legacy loan origination software and fintech speed is wide, but it is closable. Fuse exists to close it for credit unions and community banks that want to compete without becoming fintechs. Read the Rescue Fund release, see the Navigant or Canopy case study, or request a 30-minute walkthrough.
Related articles
7 Best Digital Banking Solutions for Modern Financial Institutions in 2026
5 reasons to consider whole life insurance for long-term financial planning
What to Expect When Moving Your Lending Operations to Modern Loan Origination Software
Ready to meet the AI-powered Loan Origination System?

