What Are Digital Banking Solutions and How Do They Help Banks Manage Loans and Account Opening?
Two Platforms, Two Philosophies
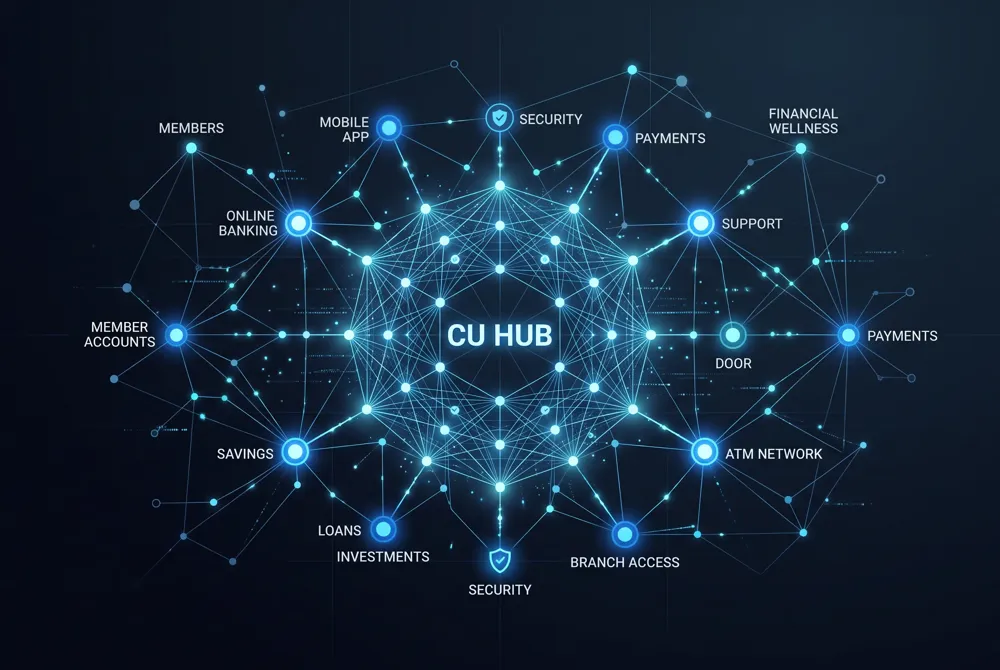
When banks and credit unions evaluate digital banking platforms, the comparison usually starts with scope: what does the system actually cover end to end? For FIS Digital One, the answer spans the full retail banking stack. FIS positions the platform as a comprehensive digital banking suite that includes online and mobile banking, digital account opening, lending origination, and the underlying core integration layer that ties them together. It is a broad, horizontal approach designed to serve large financial institutions with complex product lines and multiple channels.
FIS Digital One's lending capabilities are delivered through the FIS Loan Origination Suite, which supports consumer, mortgage, and commercial lending workflows. The platform is built to integrate with the FIS core systems (such as DNA and IBS) as well as third-party cores, giving institutions flexibility in how they deploy. For a credit union that already runs on FIS core, Digital One offers a natural path to consolidate digital channels. For those on other cores, the integration layer becomes the primary selling point, though it also becomes the primary source of implementation complexity.
Where FIS Digital One Excels
FIS Digital One's strength lies in its breadth. It is a true digital banking platform that covers account opening, payments, lending, and ongoing account management in a single vendor relationship. The platform benefits from FIS's scale, with the resources to maintain enterprise-grade security, compliance, and uptime. For institutions that prioritize a single vendor across many channels, FIS Digital One reduces the need to manage multiple point solutions. The platform also supports the kind of white-label customization that large institutions expect, allowing each bank or credit union to present the digital experience under its own brand.
Where FIS Digital One Falls Short
The trade-off is speed and flexibility. FIS Digital One is built as a comprehensive suite, which means changes often require core system involvement. Adding a new product, changing a workflow, or automating a decision typically requires IT resources and project timelines that stretch beyond the buyer's expectations. For credit unions used to the agility of point solutions or fintech partnerships, the FIS platform can feel rigid. The platform also carries a pricing model that scales with institution size and transaction volumes, which can become costly as digital adoption grows. For community banks and credit unions, the enterprise-grade feature set is often more than they need, and the implementation effort can outpace the value.
FIS Digital One is best suited for larger institutions that already have FIS core systems and want to consolidate digital channels under one vendor. It is a poor fit for institutions looking for rapid automation, low-cost deployment, or the ability to iterate without core involvement. The platform's strength is stability and breadth, not speed or flexibility.
| Aspect | FIS Digital One | Fuse |
|---|---|---|
| Scope | Full digital banking suite incl. lending | Focused LOS + account opening + automation |
| Core dependency | Tight integration with FIS cores | Core-agnostic, works with any LOS |
| Automation depth | Limited; rules-based, needs IT | AI agents on core data, auto-decisioning |
| Implementation | Long, requires core team | Weeks, with automation coach |
| Pricing | Scale-based, often high | Flat $100k/yr (credit unions $50k), $0 implementation |
FIS Digital One's Digital Banking Scope

When comparing loan origination platforms, the first question is usually about workflow breadth: how much of the lending journey does the product actually own? FIS Digital One starts with a strong answer. It is a modular digital banking platform that wraps account opening, loan origination, and ongoing self-service channels into a single customer-facing layer. For a bank or credit union, that means a member can open an account, apply for a loan, and manage both from the same login, without re-entering data or switching channels.
Digging deeper, though, the scope narrows. FIS Digital One behaves primarily as a digital front end. It excels at capturing applications, gathering documents, and presenting decisions, but the heavy lifting of loan decisioning, pricing, and portfolio management typically still happens in a separate core or loan origination system. FIS's own loan origination solution sits alongside Digital One rather than inside it. So while the member experience feels unified, the institution often manages two or more systems behind the scenes, which reintroduces the integration and reconciliation work that a true end-to-end platform is meant to eliminate.
How Fuse Compares on Breadth
Fuse approaches the same problem from the opposite direction. Instead of bolting account opening and lending onto a digital banking layer, Fuse is built from the ground up as a single digital account opening and loan origination system that spans the entire lifecycle: applicant portal, decision engine, document automation, agent workspace, and account opening. There is no separate core module to reconcile and no handoff between systems. What the member sees in the portal is the same data the auto-decisioning engine uses to make a credit decision.
Scope. FIS Digital One covers the digital channel layer; Fuse covers origination from application to decision to account opening.Automation depth. FIS Digital One digitizes the front end; Fuse automates the full back office, including document reading, validation, fraud checks, and auto-decisioning on core data fields.Integration model. FIS Digital One often requires integration with a separate LOS or core; Fuse replaces the fragmented stack with one system and 200+ pre-built integrations.Implementation. FIS Digital One is a large enterprise deployment; Fuse ships in weeks with a dedicated automation coach.
| Capability | FIS Digital One | Fuse |
|---|---|---|
| Digital banking front end | Yes, modular | Yes, built-in |
| Loan origination | Separate product | Core focus |
| Auto-decisioning | Partial | 100% of core data fields |
| Document automation | Basic | AI-powered extraction |
| Deployment timeline | Months | Weeks |
For credit unions and community banks evaluating their options, the practical takeaway is this: if you already run FIS Digital One and are comfortable with the integration overhead, it can work. But if you are looking for a platform that modernizes the entire lending operation, not just the member-facing layer, Fuse's approach deserves a closer look.
Fuse's Lending Automation Focus
FIS Digital One is a comprehensive digital banking platform designed for financial institutions that want a unified, cloud-based solution. It consolidates digital account opening, lending, and business channels into a single system, which is a meaningful advantage for credit unions looking to retire fragmented point solutions.
The platform is built on an open architecture, allowing institutions to integrate with their existing core system and third-party services through APIs. This flexibility reduces the need for rip-and-replace projects, a common pain point in the industry. FIS positions Digital One as a way to accelerate time-to-market for new digital products without requiring deep in-house IT resources.
What FIS Digital One Covers
Account Opening. Digital account opening spans retail and business, with features like document capture, identity verification, and e-signature. This addresses the onboarding friction that often drives members away.Lending. Digital lending capabilities support consumer and small business loan applications, including decisioning and funding. This can replace outdated LOS modules from core providers.Business Banking. Business channels cover cash management and account services, helping institutions serve commercial members with a modern interface.
For credit unions, the appeal lies in the breadth of the platform. Instead of stitching together a loan origination system, a separate account opening tool, and a business portal, FIS Digital One provides a single layer. However, like any legacy vendor offering, the depth of functionality varies by module, and institutions should evaluate whether it meets their specific automation goals.
FIS has invested heavily in modernizing this platform, and it integrates with their core processing systems. But for credit unions seeking faster innovation, the question is whether a large vendor's roadmap aligns with the agility of a Fuse or other specialists. FIS Digital One is a solid choice for institutions already on FIS core, but it may not offer the same level of automation depth as dedicated AI-native platforms.
| Aspect | FIS Digital One | Fuse |
|---|---|---|
| Automation Depth | Standard digital workflows | AI-native auto-decisioning on core data |
| Implementation | Typical enterprise deployment | Guaranteed under 1 month for integrations |
| Pricing Model | Per-module, variable fees | Flat $100k/year, $0 implementation |
FIS Digital One's Digital-First Business Banking
FIS Digital One is the retail digital banking suite from FIS, a global financial technology provider serving thousands of institutions. It gives banks and credit unions a unified digital channel layer spanning online banking, mobile, and every self-service touchpoint. Rather than a single product, Digital One operates as a modular platform that institutions can deploy incrementally, which keeps it attractive to organizations that already run a core from FIS and want a faster path to a modern digital experience.
The platform consolidates the user experience across web and mobile, while offering APIs and pre-built connectors to FIS core systems like DNA, and to third-party apps. For many FIS-core shops, Digital One is the default front end because it reduces integration complexity and lets staff launch new digital features without waiting on core releases. That tight coupling is both the main advantage and the main constraint, since the platform is built to operate best inside the FIS ecosystem.
Core capabilities
Digital One focuses on the routine, high-volume digital banking functions that members use daily. It does not try to replace the core or originate every loan type itself; instead, it layers a digital experience on top of existing back-office systems.
- Online and mobile banking with bill pay, transfers, and e-statements
- Person-to-person payments, mobile check deposit, and card controls
- Digital account opening and basic consumer loan applications
- Configurable dashboards and alerts for members
- Integration with FIS core systems plus select third-party providers
Because it is modular, institutions can deploy only the modules they need and phase in the rest. That flexibility helps mid-size and smaller FIS-run banks avoid a rip-and-replace project while still modernizing the member-facing layer.
Integration and deployment
FIS markets Digital One as a managed, cloud-based offering, which removes the burden of running on-premise infrastructure. The platform ships with pre-built connectors to FIS core systems and to common payments and fraud vendors, which shortens the typical integration timeline. Institutions that are already standardizing on FIS will find that Digital One's road map tracks the vendor's broader product direction, making it a lower-risk choice from a vendor-alignment standpoint.
That said, the platform is not designed as an open marketplace where institutions can freely mix and match best-of-breed lending, account opening, or decisioning tools. Teams that want to bring in a specialist vendor, such as a dedicated loan origination system or a modern digital account opening platform, will likely find that Digital One's integration points are more limited and that the pace of release is tied to FIS's own schedule.
Fees and contract model
FIS does not publicly list pricing for Digital One; like most legacy enterprise software, it quotes per-module and per-account fees that scale with the size of the institution and the number of active digital users. Contracts typically run multi-year and include implementation, which can stretch over many months depending on the complexity of the core integration and the amount of configuration needed.
| Dimension | FIS Digital One | Fuse |
|---|---|---|
| Deployment | Cloud-hosted module layer | Full-stack LOS & account opening |
| Integration | Best with FIS cores | 200+ pre-built integrations, core-agnostic |
| Pricing | Per-module, custom quote | Flat $100K/yr ($50K for small CUs), $0 implementation |
| Automation | Configurable workflows | AI agents + weekly releases, ~1% new automation/week |
| Contract | Multi-year, vendor-aligned | Flat-fee with Automation Guaranteed |
| Best for | FIS-core institutions | Credit unions wanting fintech speed |
Fuse's Core Advantage: Speed and Automation
Vendor guarantees sound impressive until the fine print arrives. Most LOS and digital banking contracts are full of legal disclaimers and carefully worded outcome language, which is why procurement teams learn to read for the commitments that actually matter. The Fuse Automation Guaranteed program takes a different approach by putting three specific, contractual commitments in writing. None of them are success-based pricing or vague promises about results. Instead, they are operational guarantees that shape how the platform is delivered and supported every week.
The first commitment covers new integrations. If a credit union needs a new connection, whether to a core processor, a fraud vendor, or a data aggregator, Fuse delivers it in under one month at no extra cost. That single line removes the most common source of project delay and surprise line items. The second guarantee is about cadence: product releases ship weekly. Teams do not wait months for a feature or a fix, and the platform improves on a predictable schedule. The third commitment is about automation depth. Fuse can auto-decision on 100% of core data fields, meaning loan decisions can run end-to-end without manual review on every field a lender typically touches.
Notice what these guarantees do not promise. There is no language about a specific percentage of auto-decisions, no promised reduction in funding time, and no outcome-based fee structure. Fuse does not claim to "guarantee" a 40% auto-decision rate or a 71% annual automation gain. Those figures represent what customers achieve on average when they follow the proactive automation model, but they are not contractual. The guarantees are deliberately narrow because they are operational commitments that Fuse controls. That distinction matters when executives are comparing vendor claims. A promise to deliver integrations quickly, ship weekly, and decision on all core fields is measurable and auditable. A promise to produce a certain business outcome depends on how much the lender actually adopts the technology.
The pricing model reinforces this discipline. Fuse charges a flat $100,000 per year, or $50,000 for smaller credit unions, with $0 implementation and $0 variable fees. That means the cost of automation is predictable from day one, and the vendor earns the same regardless of how much or how little automation a client deploys. Because there is no per-loan fee and no success-based kicker, Fuse's incentive is to help clients actually use the platform well, not to drive volume through a particular pricing gate. In March 2026, Fuse launched the $5M Fuse Rescue Fund, which lets the first 50 qualifying credit unions use the platform free until their existing loan origination system contract expires. After that, they move to the same flat-fee subscription.
Integration guarantee. New integrations ship in under one month at no extra cost, covering connections to cores, fraud vendors, and other systems. This is a contractual commitment, not a target.Release cadence. Product releases ship every week, so improvements and fixes reach credit unions on a predictable schedule without long release cycles.Auto-decision coverage. Fuse can auto-decision on 100% of core data fields, including custom attributes and charge-off history, enabling full end-to-end automation without manual touch.
Pricing: Flat Fees vs. Legacy Tolls
Fuse's commercial model is deliberately simple. Instead of per-seat fees, implementation charges, or variable costs tied to loan volume, the platform runs on a flat annual subscription: $100,000 per year for most institutions, or $50,000 for smaller credit unions. There are no implementation fees and no variable fees. That means no surprise line items when loan volume spikes, and no disincentive to grow your portfolio. The pricing is the same whether you fund 10 loans or 10,000.
This is not a success-based or outcome-based pricing structure. Fuse does not charge a percentage of interest, a per-loan fee, or any amount "only when results materialize." The flat fee is the entire cost of the platform, full stop. For executives who have watched legacy vendors stack on per-user, per-module, and per-integration surcharges, this predictability is a meaningful contrast. You know your technology cost before the first dollar of revenue comes in.
Fuse also stands behind the platform contractually. Every Fuse contract includes an Automation Guaranteed commitment covering three specific items: new integrations delivered in under one month at no extra cost, weekly product releases, and the ability to auto-decision on 100% of core data fields. These are not aspirational goals; they are written into the agreement. If Fuse misses a monthly integration delivery, the client has contractual recourse.
A separate commitment, Proactive Automation, is an operating model rather than a contractual guarantee. Each client is paired with a dedicated Automation Coach who meets every two weeks to identify and ship the next highest-impact automation. The typical outcome is approximately 1% new automation per week, which compounds to roughly 71% in the first year. These are average customer outcomes, not contractual promises. Fuse frames them honestly: "customers achieve on average," not "guaranteed results." The distinction matters because it sets realistic expectations without overpromising.
To lower the barrier to entry further, Fuse launched the $5M Fuse Rescue Fund in March 2026. The first 50 qualifying credit unions get free use of the platform until their existing loan origination system contract expires, then transition to the standard flat-fee subscription. This is not a teaser rate or a freemium tier; it is a direct financial bridge for institutions that are locked into legacy contracts but want to start modernizing immediately.
| Commitment | What It Covers | Contractual or Average? |
|---|---|---|
| Automation Guaranteed | Integrations in <1 month, weekly releases, auto-decision on 100% of core data fields | Contractual |
| Proactive Automation | Dedicated coach, 1% automation per week, ~71% in year one | Average customer outcome |
| Pricing | Flat $100k/yr ($50k for smaller CUs), $0 implementation, $0 variable fees | Fixed contract |
The Modern Alternative to Legacy LOS
Credit unions and community banks evaluating loan origination platforms in 2026 face a crowded market. Three names come up most often in competitive reviews: FIS Digital One, MeridianLink, and nCino. Each takes a different approach to lending automation, and the right choice depends on your institution's size, technology appetite, and tolerance for vendor lock-in.
This guide compares the three platforms across the criteria that matter most to lending and operations leaders: implementation timeline, automation depth, pricing transparency, and total cost of ownership. It closes with a look at how Fuse positions itself against all three as a purpose-built alternative for credit unions that want fintech speed without becoming fintechs themselves.
How FIS Digital One Approaches Digital Banking
FIS Digital One is part of FIS's broader digital banking suite, designed to help financial institutions offer mobile and online banking, account opening, and lending capabilities under one vendor umbrella. It leans on FIS's existing core processing relationships, which can ease integration for banks already on FIS core systems. However, institutions typically report longer implementation cycles for full lending automation, and the platform's modular architecture means assembling the right combination of modules often requires professional services support.Implementation. FIS Digital One generally requires a multi-quarter rollout, especially when integrating loan origination with existing core systems. Timelines often stretch 6 to 12 months depending on the modules selected.Automation depth. The platform automates specific steps like document collection and basic decisioning, but many credit unions report manual handoffs remain for exceptions, fraud checks, and complex commercial loans.Pricing model. FIS typically prices per module with variable fees tied to transaction volume. Final costs often depend on the size of the institution and the number of add-ons, making budgeting less predictable.Ideal fit. Best suited for mid-size to large banks already deeply embedded in the FIS ecosystem, where standardization across the enterprise takes priority over lending-specific speed.
MeridianLink's Point Solution for Consumer Lending
MeridianLink is a well-known name in credit union lending, offering a LOS that focuses on consumer and indirect lending. It excels at specific functions like loan origination workflows, decisioning, and document management. Many credit unions use MeridianLink alongside their core system, appreciating its familiarity and the fact that it handles the lending-specific processes well.Implementation. MeridianLink implementations are generally faster than full-platform replacements, often completing in 3 to 6 months. However, integration with core systems and other lending tools can still require significant IT resources.Automation depth. Automation is strongest in consumer lending workflows, but the platform relies heavily on rules-based logic. Advanced features like auto-decisioning on all core data fields, document intelligence, and AI-driven exceptions are limited or require additional vendor partnerships.Pricing model. MeridianLink uses a subscription model, but pricing scales with loan volume and the number of users. Variable fees and implementation costs can add up, especially for institutions with high application volume.Ideal fit. Best for credit unions that need a proven consumer lending LOS and already have strong core integration in place, but don't require deep automation across the full lending lifecycle.
nCino's Enterprise Banking Platform
nCino markets itself as the leading cloud banking platform, with a strong presence in commercial and small business lending. Its Bank Operating System is designed to streamline the entire client lifecycle, from account opening to loan origination. nCino's strength lies in its commercial lending capabilities and its tight integration with Salesforce, which powers its CRM functionality.Implementation. nCino implementations are typically lengthy, often running 9 to 18 months, particularly for institutions replacing multiple legacy systems. The Salesforce dependency means the bank's IT team must also manage that underlying platform.Automation depth. nCino automates core lending processes well for commercial and small business, but its automation capabilities for consumer and indirect lending are less comprehensive. AI features exist but are often add-ons that require separate contracting.Pricing model. nCino is known for its premium pricing, often exceeding $1 million annually for mid-size institutions when you factor in implementation, integration, and ongoing maintenance. Variable fees are less common, but the upfront investment is significant.Ideal fit. Best for large banks and commercial lenders that prioritize CRM integration and have the budget and IT resources to support a complex, long-term platform deployment.
Where Fuse Stands Against the Field
Fuse enters this competitive landscape as a different kind of option. Built specifically for credit unions and community financial institutions, Fuse replaces fragmented legacy stacks like MeridianLink, FIS, and nCino with a single system that spans the applicant portal, decision engine, document automation, agent workspace, and account opening. It ships with 200+ pre-built integrations, and business users configure rules, workflows, and screens with no code.
Where Fuse diverges most sharply is in its operating model and pricing. Fuse's proactive automation program assigns each client a dedicated Automation Coach who meets every two weeks to identify and ship the next highest-impact automation. Customers achieve on average approximately 1% new automation per week, or roughly 71% in the first year. That's an average customer outcome, not a contractual guarantee.
The contractual guarantee, called Automation Guaranteed, is written into every Fuse contract and covers three items only: new integrations delivered in under one month at no extra cost, weekly product releases, and the ability to auto-decision on 100% of core data fields. Pricing is flat at $100,000 per year ($50,000 for smaller credit unions), with $0 implementation and $0 variable fees. In March 2026, Fuse launched the $5M Fuse Rescue Fund, giving free use of the platform to the first 50 qualifying credit unions until their existing LOS contract expires, then transitioning to the flat-fee subscription.
Representative customer outcomes illustrate the impact. Vibrant Credit Union, working through the Drivata auto-lending CUSO, cut funding time from three days to 1.2 minutes and grew indirect volume over 40%. Canopy Credit Union, a $200M CDFI, turned on auto-decisioning after five years of being unable to under their prior LOS, and is on track to 40% auto-decisions within six months. Navigant Credit Union, with $4B in assets, launched a fully automated credit card program with end-to-end auto-decisioning on core data.
| Criteria | FIS Digital One | MeridianLink | nCino | Fuse |
|---|---|---|---|---|
| Best for | FIS-core banks | Consumer lending | Commercial banks | Credit unions |
| Automation depth | Moderate | Limited to consumer | Commercial-focused | Full lifecycle |
| Pricing | Per module | Volume-based | Premium | Flat $100K/yr |
| Implementation | 6-12 months | 3-6 months | 9-18 months | Weeks to months |
| Contractual guarantee | None | None | None | Automation Guaranteed |
Proven Customer Outcomes

For credit unions and community institutions, the decision between Fuse and FIS Digital One often comes down to architecture. FIS spans the broader FIS ecosystem, while Fuse delivers a focused, AI-native platform designed specifically for lending and account opening. Where FIS emphasizes its full-stack integrations, Fuse prioritizes deep automation and speed, without requiring months of implementation.
Fuse's differentiation stands on three pillars. First, its AI agents handle narrow, concrete tasks: document reading, fraud checks, and auto-decisioning on core data. Second, the platform ships weekly, so institutions adopt improvements continuously, not in annual upgrades. Third, Fuse charges a flat annual fee with no implementation costs, unlike the variable or per-seat models common in the industry.
Automation in Practice: Measured Outcomes
Fuse's operating model, proactive automation, pairs each client with a dedicated Automation Coach who meets biweekly to identify and implement the next high-impact workflow. On average, customers achieve approximately 1% new automation per week, reaching about 71% in the first year. This is a typical outcome, not a contractual promise. Alongside this, Fuse's contractual commitments cover three specific items: new integrations delivered within one month, weekly product releases, and the ability to auto-decision on 100% of core data fields.
The results speak in concrete terms. Vibrant Credit Union, working through the Drivata auto-lending CUSO, cut funding time from three days to 1.2 minutes and grew indirect volume by over 40%. Canopy Credit Union, a $200M CDFI, enabled auto-decisioning after five years of being unable to do so under its previous system, now on track to reach 40% auto-decisions within six months. These are not isolated incidents but patterns seen across Fuse's 100+ institutional clients.
Pricing That Fits the Mission
Fuse's pricing is refreshingly straightforward: $100,000 per year for most institutions, $50,000 for smaller credit unions, with $0 implementation and $0 variable fees. This flat structure, announced alongside the $5M Fuse Rescue Fund, offers free platform use for the first 50 qualifying credit unions until their existing loan origination system contract expires, easing the transition burden.
| Aspect | Fuse | FIS Digital One |
|---|---|---|
| Pricing Model | Flat annual fee; no success fees | Typically variable or per-seat |
| Automation Approach | AI agents for narrow tasks | Broader platform integrations |
| Deployment | Single-tenant, weekly releases | Dependent on core ecosystem |
| Customer Outcome | 1% automation per week | Varies by implementation |
For executives evaluating digital lending platforms, the Fuse model removes guesswork. No hidden fees, no painful migrations, and a clear path to automation. As the industry moves toward digital-first expectations, digital banking solutions must deliver real, measurable value, and Fuse designs its platform to do exactly that.
Choosing the Right Fit for Your Institution
Fuse enters these conversations with a different playbook. Rather than another layer of point solutions or a toolkit that demands a data science team, it is a single, AI-native platform built for the way credit unions actually operate. The digital account opening experience, the lending workflow, and the decisioning logic all live in one place, with no-code configuration for the business team.
The outcomes show up in named, real-world deployments. Vibrant Credit Union, lending through the Drivata auto-lending CUSO, cut funding time from three days to 1.2 minutes and grew indirect volume by over 40%. Canopy Credit Union, a $200M CDFI, turned on auto-decisioning for the first time in five years and is on track to hit 40% auto-decisions within six months. Navigant Credit Union($4B) launched a fully automated credit card program with end-to-end auto-decisioning on core data.Proactive automation. Every client gets a dedicated Automation Coach who meets biweekly to identify the next highest-impact workflow. Customers achieve on average roughly 1% new automation per week, or about 71% in the first year. These are typical outcomes, not contractual guarantees.Automation Guaranteed. Written into every contract, this covers three commitments: new integrations delivered in under one month at no extra cost, weekly product releases, and the ability to auto-decision on 100% of core data fields.
Fuse is not a fintech that happens to serve banks, nor a horizontal LOS for any vertical. It is built specifically for traditional financial institutions, credit unions first, delivering fintech-grade speed without requiring the institution to become a fintech itself. The platform ships weekly, is single-tenant and SOC 2 compliant, and carries a flat price tag: $100,000 per year, or $50,000 for smaller credit unions, with $0 implementation and $0 variable fees. In March 2026, Fuse launched the $5M Fuse Rescue Fund, offering free platform use for the first 50 qualifying credit unions until their existing LOS contract expires.
| Capability | Fuse | Typical Legacy LOS |
|---|---|---|
| Auto-decisioning | 100% of core data fields | Limited to pre-set rules |
| Integrations | New ones in <1 month, included | Months of custom work |
| Pricing | Flat, no implementation fees | Variable, per-seat or per-loan |
Making the Strategic Decision
Digital One is a comprehensive digital banking platform from FIS, designed for banks and credit unions that want to consolidate multiple channels, from online and mobile banking to cash management and payments. It suits institutions seeking an established, enterprise-grade suite backed by a major provider. Fuse, by contrast, targets credit unions and community financial institutions that want to replace fragmented legacy systems with a faster, more agile lending and account opening platform. Both handle core digital banking functions, but they start from different assumptions about what a modern financial institution needs.
Core Functionality: Breadth vs. Focus
Digital One covers a wide span of digital channels, so a single FIS contract can deliver online banking, mobile apps, bill pay, and business cash management. That breadth helps institutions that want one vendor for many touchpoints. Fuse concentrates on the highest-friction parts of lending and account opening: applicant portals, decision engines, document automation, and account opening workflows. Instead of spreading across every banking channel, Fuse builds depth where manual work slows down loan and deposit growth. Institutions that already have a solid general-purpose digital channel often find Fuse fills the gaps where core-based modules lag.
Scope. Digital One spans online banking, mobile, payments, and cash management. Fuse focuses on lending and account opening workflows from application to funding.Integration. Digital One integrates with FIS core systems and a broader FIS ecosystem. Fuse ships with 200+ pre-built integrations and connects to any core, including FIS, Fiserv, Jack Henry, and Corelation, without requiring core code changes.Intelligence. Digital One embeds analytics and personalization within its suite. Fuse applies AI agents that read documents, validate applications, detect fraud, and auto-decision on 100% of core data fields, plus custom attributes and charge-off history.
Implementation and Ongoing Cost
Digital One typically requires professional services for setup and configuration, and its pricing model is not published, reflecting its enterprise orientation. Fuse offers a flat fee of $100,000 per year for most institutions and $50,000 for smaller credit unions, with $0 implementation and $0 variable fees. That simplicity appeals to leaders who have seen projects balloon in cost and timeline. Fuse also commits to shipping new features weekly and delivering new integrations in under one month at no extra cost, so the platform evolves without change orders.
Beyond cost, the operational model differs. Fuse assigns a dedicated Automation Coach who meets every two weeks to identify the next highest-impact automation, helping institutions achieve on average approximately 1% new automation per week, or roughly 71% in the first year. That is an average customer outcome, not a guarantee. Digital One relies more on the institution's internal team to drive adoption and configuration, which can strain resources in smaller shops.
Automation Capabilities and AI Agents
Fuse's AI agents perform specific, narrow functions: reading documents and extracting data, validating applications, verifying fraud, sending outbound borrower communications, and auto-decisioning on any core data field. These agents apply configured rules and AI inference at the point of action, and they are not self-training or continuously learning. Digital One offers automation within its suite, but it is not designed as a specialized lending automation engine. For credit unions that want to move from manual underwriting to high auto-decision rates, Fuse's agents tackle the work that consumes loan officer hours.
Real customer results illustrate the difference. Navigant Credit Union, a $4B institution, launched a fully automated credit card program with end-to-end auto-decisioning on core data. Canopy Credit Union, a $200M CDFI, turned on auto-decisioning after five years of being unable to under their prior LOS, on track to 40% auto-decisions within six months. Vibrant Credit Union cut funding time from three days to 1.2 minutes and grew indirect volume by over 40% through the Drivata auto-lending CUSO. These are representative, not typical, but they show what focused automation can achieve.
Vendor Relationship and Support Model
Digital One is one product within a large vendor's portfolio, so support and product direction sit inside FIS's broader roadmap. That can mean competing priorities across business lines. Fuse is built specifically for credit unions and community banks, with a founding team that focuses solely on this segment. The company is backed by $25M+ from investors behind Chime and OpenAI, and it became an officially resold product of FIS in January 2026, which gives institutions confidence in its longevity. Infrastructure is single-tenant and SOC 2 compliant, addressing security concerns that arise with cloud platforms.
The support cadence also differs. Fuse's weekly releases and biweekly coaching sessions mean continuous improvement is baked in. For leaders who remember legacy LOS implementations that dragged on for years, this operating model offers a more predictable path. Digital One can be the right choice for institutions that want a broad digital suite from one established vendor. Fuse appeals to those who want to modernize lending specifically, without ripping out their entire core or becoming a fintech.
Which One Fits Your Institution?
Budget. Digital One's cost depends on modules and services. Fuse's flat fee of $100K/year ($50K for smaller credit unions) with no implementation or variable fees makes budgeting predictable.Core focus. If lending and account opening are your top pain points, Fuse's specialized automation delivers faster ROI. If you need a broad digital channel overhaul, Digital One's suite may fit better.Speed of change. Fuse ships weekly and includes new integrations in under a month, while larger vendor platforms often have longer release cycles. Institutions that value rapid iteration will prefer Fuse.
| Feature | Fuse | Digital One (FIS) |
|---|---|---|
| Primary focus | Lending and account opening automation | Broad digital banking suite |
| Pricing | $100K/year flat ($50K for small CUs) | Not published, typically custom |
| Implementation | $0, no variable fees | Professional services required |
| Integrations | 200+ pre-built, all cores | Best with FIS core |
| AI agents | Document reading, validation, fraud, auto-decisioning | Limited, not specialized |
| Support model | Dedicated Automation Coach, weekly releases | Standard vendor support |
| Best for | Credit unions and community banks wanting fintech speed | Institutions wanting one vendor for many channels |
Choosing between Fuse and Digital One ultimately depends on your institution's priorities. If you want to automate lending workflows without a massive implementation project, Fuse offers a focused, flat-fee alternative. To see whether it fits your operations, request a 30-minute walkthrough with the Fuse team and bring your current pain points. That conversation will clarify whether the platform's automation agents and coaching model address your biggest bottlenecks.
Related articles
7 Things to Look for When Choosing Bank Account Opening Software in 2026
5 Key Benefits of Using a Digital Lending Platform for Your Bank
How to Find Commercial Lending Software That Integrates With Your Bank Loan Software
Ready to meet the AI-powered Loan Origination System?

