How to Integrate Digital Account Opening with Modern Loan Origination Software
Why Connect Opening and Lending
Digital account opening and loan origination software often sit in separate systems, even though both rely on overlapping member information. The result is familiar to credit union teams: members may enter the same details more than once, staff rekey data, and applications pass between departments through manual handoffs. A CUInsight analysis of unified account opening and lending describes how these silos can slow approvals and make consistent checks harder.
Those steps create work beyond the application itself. Staff must reconcile records, chase missing information, and keep separate workflows moving. Fragmented data can also make it harder to see an application’s status or maintain a clear audit trail. Connecting systems is therefore an operating decision, not just a redesign of the online form.
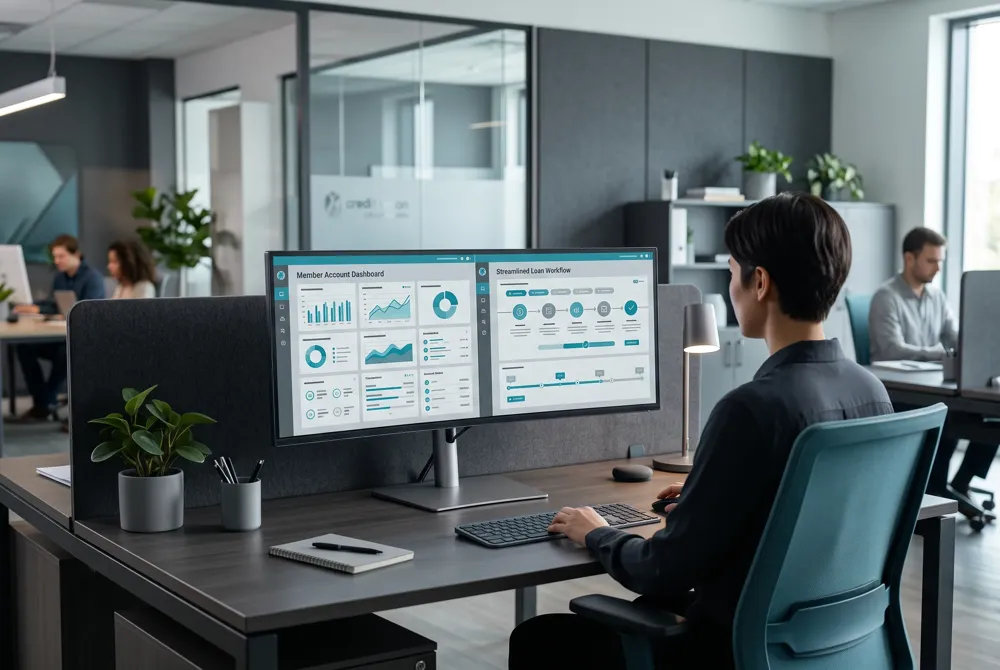
A connected platform can carry information from intake through decisioning and documentation, then link an approved loan to account opening where the member journey calls for it. It should also work with the institution’s core and existing services rather than require a wholesale replacement. Fuse brings account opening and lending workflows into one configurable system, with 200+ pre-built integrations and no-code configuration. Credit unions can assess the fit by mapping where data is entered, handed off, and checked today.
What Loan Origination Software Handles

Loan origination software coordinates lending work from application intake through review, decisioning, documentation, and funding. Its scope varies: some systems focus on preparing loan documents, while others support a broader process from application to closing.
A system may collect and validate application information, present files for staff review, apply configured lending rules, track workflow stages, and prepare documents for completion. These tools support staff oversight, but they do not remove the need for institutional policies or human judgment where review is required.
Lending-specific tasks remain distinct from digital account opening. A loan workflow assesses and processes a request for credit; account opening establishes the member’s deposit relationship. Connecting the two can let relevant information move between journeys and reduce repeated entry and manual handoffs, as described in CUInsight’s account-opening and loan-origination analysis.
For credit unions evaluating loan origination software, the practical question is what staff can manage in one workflow and what still requires a separate tool. Fuse brings the applicant portal, decision engine, document automation, staff workspace, and account opening together, with more than 200 pre-built integrations.
Fuse’s AI agents have defined jobs: reading documents and extracting data, validating documents, checking for fraud, sending borrower communications, and auto-decisioning with configured rules and AI inference. This is task-specific automation, not a claim that the system learns from past loan outcomes.
Map the Shared Member Journey

Digital account opening and loan origination software work best as connected stages, not isolated applications. A credit union can link intake, identity and information checks, lending review, decisioning, document workflows, and account opening in one platform or through systems connected to its core.
When systems do not share information, members may have to submit the same details more than once, while staff transfer or reconcile data between teams. A January 2026 CUInsight article on unified account opening and loan origination describes these repeated steps and handoffs as sources of delay. It reports that some financial institutions have achieved up to 50% faster account opening and loan processing. Treat that as an upper-end reported result, not a promised outcome.
APIs can connect workflows to external services for KYC, AML, e-signature, and third-party data. Before selecting software, confirm which integrations are already available, what information each connection exchanges, and how records reach the core. Those details determine whether a connected journey reduces manual work or simply shifts it to another queue.
Fuse combines digital account opening and lending workflows in one platform, with more than 200 pre-built integrations and no-code configuration for rules, screens, and workflows. Its agents handle defined tasks such as document extraction and validation, fraud verification, and auto-decisioning. Under Automation Guaranteed, Fuse commits to new integrations in under one month at no extra cost, weekly product releases, and the ability to auto-decision on 100% of core data fields.
Follow the Lending Workflow
Loan origination software can support a lending workflow from application intake through funding. The exact stages depend on the institution’s policies, products, and system scope. A CUInsight overview of unified account opening and lending describes how connected workflows can reduce duplicate steps and manual handoffs.
At intake, staff or an applicant can submit an application and supporting documents. The system can collect and validate those documents, check fraud indicators, and route the file for underwriting. Digital account opening adds the steps needed to establish the member’s account, while the credit union’s rules still govern lending review and decisions.
Fuse’s agents handle defined tasks within that process. They extract data from documents, validate information, verify fraud indicators, and send outbound communications when information is missing. Configured rules can also auto-decision applications using core data fields. Staff retain oversight of exceptions and decisions that require judgment.
These functions do not mean that automation replaces underwriting judgment or learns from prior loan outcomes. The institution sets the rules and workflow. A connected platform keeps intake, review, communication, and funding steps in one operational path, while staff remain responsible for policy and oversight.
Assess Fit Before Selecting Software
Choosing loan origination software starts with the work, not the demo. Map how members open accounts and apply for loans, then trace what staff do at each stage. Mark repeated data entry, manual handoffs, and separate journeys that should connect. A CUInsight guide to unified account opening and loan origination recommends auditing current processes before evaluating platforms.
Define which products and channels belong in scope, including consumer, indirect, and small-business lending, plus digital account opening. Then check whether the platform fits the credit union’s core and other systems. Ask which integrations are already available, how new ones are delivered, and whether business users can change rules, workflows, and screens without code. Fuse includes 200+ pre-built integrations and no-code configuration, so operations teams can adapt processes without waiting for custom development.
Test staff controls with real scenarios. Can applications move through stages according to role and policy? Can staff see the information and documents needed for review? How are exceptions routed, decisions governed, and records retained? Confirm that automation supports the credit union’s review model rather than obscuring it. Fuse’s document-reading, validation, fraud-verification, and decisioning agents handle defined tasks; the institution configures the rules they apply.
Compare total costs, not a vendor’s listed price in isolation. Ask for implementation fees, annual subscription costs, variable charges, and the price of future configuration or integrations. Review release cadence and written commitments alongside the commercial proposal. Fuse charges $100,000 per year, or $50,000 for smaller credit unions, with $0 implementation and $0 variable fees.
Fuse’s contractual Automation Guaranteed commitments are specific: new integrations delivered in under one month at no extra cost, weekly product releases, and the ability to auto-decision on 100% of core data fields. Check that any vendor promise is written into the contract and distinguish it from a typical customer outcome. A 30-minute walkthrough using the credit union’s own workflow is a practical next step.
Separate Commitments From Outcomes

For credit union leaders evaluating digital account opening and loan origination software, a contractual commitment and an average customer result are not the same thing. Fuse’s contract covers three specific commitments: new integrations delivered in under a month at no extra cost, weekly product releases, and the ability to auto-decision on 100% of core data fields. Automation rates are not part of that guarantee.
The separate operating model is proactive automation. Each Fuse client works with a dedicated Automation Coach every two weeks to identify and ship the next high-impact workflow automation. On average, Fuse customers achieve approximately 1% new automation per week, or roughly 71% in the first year. These are typical customer outcomes, not promised results for every institution. The CUInsight discussion of unified account opening and loan origination also recommends assessing current journeys before selecting an integrated approach.
Institution-specific results show what this model can support. Navigant Credit Union launched an automated credit card program with end-to-end auto-decisioning on core data. Canopy Credit Union enabled auto-decisioning after five years of being unable to do so under its prior LOS. Canopy is on track to reach 40% auto-decisions within six months, a target for that credit union, not a forecast for every Fuse client.
These examples are useful when assessing what a platform can make possible, but they do not replace workflow-level diligence. Credit unions can compare their current processes with the capabilities described in this guide to digital lending platforms and traditional loan origination software.
Make Integration a Measurable Decision
Begin with a map of the credit union’s current digital account opening and lending journeys. Mark where staff re-enter data, where applications change hands, which systems own each record, and where core connections or compliance checks occur. A CUInsight analysis of unified account opening and loan origination also recommends auditing existing journeys before evaluating integrated platforms.
Then compare the proposed loan origination software against that map. Test the workflows the institution actually needs, confirm how the platform connects to the core and existing providers, and identify who owns each decision, document, and exception. A unified workflow has value only when it fits the credit union’s processes and makes handoffs and system responsibilities clear.
Fuse serves credit unions with one platform spanning account opening, lending workflows, integrations, and decisioning. Its 200-plus pre-built integrations and no-code configuration give teams concrete points to assess against their current environment. Request a 30-minute Fuse walkthrough focused on the credit union’s account-opening and lending workflows.
Start With the Workflow
Map where digital account opening and lending split today. Identify which member and application details need to move between teams, systems, and the core, then document the staff steps that follow each handoff.
Use that map to test whether loan origination software supports the credit union’s actual workflows, including document handling, decision rules, and core connections. CUInsight’s guidance on unified account opening and loan origination also recommends auditing current journeys before evaluating integrated platforms.
Fuse brings account opening and lending workflows into one platform, with 200+ pre-built integrations and no-code configuration. Request a 30-minute Fuse walkthrough focused on your institution’s integration needs, core environment, and staff workflow.
Related articles
7 Ways to Use Digital Loan Origination to Compete With Big Banks
Digital Account Opening: 5 Steps to Better User Experience for New Members
How to Integrate Digital Account Opening with Modern Loan Origination Software
Ready to meet the AI-powered Loan Origination System?

